Pensacola Beach Public Adjuster
On Santa Rosa Island, almost every storm claim comes with a water question and, before the rebuild, a permit question. We work for you, not your insurance company. Free, no-obligation damage inspection and policy evaluation.
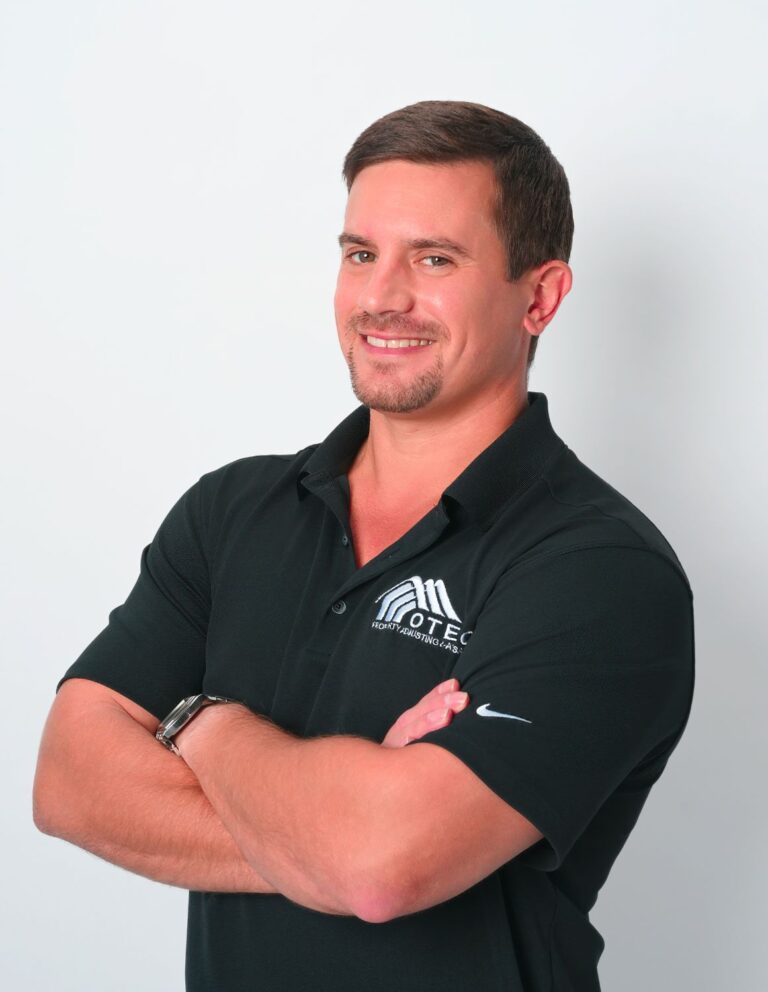
David Otero, President
Licensed Florida public insurance adjuster
7+ years of claims experience
- License W605057
- FAPIA member
- Windstorm Insurance Network member
- Rated 5.0 on Google
- Free inspection
A Pensacola Beach Public Adjuster, half an hour away
Otero Property Adjusting & Appraisals Inc represents homeowners, condo owners, rental owners and business owners on Pensacola Beach and Perdido Key. We work only for policyholders, never for insurance companies.
Our office is on West Michigan Ave in Pensacola, about 16 miles from Pensacola Beach and 26 miles from Perdido Key. That’s close enough to be on the island for your inspection without making a day of it. When you call, you talk to our Pensacola team, and David Otero oversees your claim.
- 3105 West Michigan Ave, Pensacola, FL 32526
- (850) 285-0405
Tell us where the property is, who insures it, and whether you carry a separate flood policy. We’ll set up your free inspection.
Claims we handle on Pensacola Beach
Island claims start with the Gulf: wind, surge, or both in the same night. Find the one that fits.
Hurricane damage
A hurricane hits a barrier island with wind first and water right behind it. Each goes to its own policy, so each needs its own documentation.
Flood damage
Storm surge and overwash belong to a flood policy, not your homeowners policy. We file the flood side separately so it can't be used to cut the wind side.
Roof and wind damage
Salt-laden wind strips shingles, siding and soffits. Rain that gets in through that damage is part of the wind claim.
Water damage
A failed line in a condo above or an AC overflow in an empty rental can soak several floors before anyone notices.
Commercial property claims
Beach businesses, rental buildings and condo associations carry commercial policies with their own conditions and limits.
Income loss claims
A rental unit that sits empty during repairs is lost income. It's only paid when it's claimed and backed by booking records.
Mold damage
Gulf humidity turns trapped water into mold fast. Many policies cap mold, so the source and date need to be on record early.
Fire and smoke damage
In a condo tower, smoke travels through halls and shared ducts. Cleaning and contents in every affected unit belong in the claim.
Where Pensacola Beach claims come up short
Hurricane Opal came ashore near Pensacola Beach on October 4, 1995. The Florida Department of Environmental Protection later found that Opal damaged or destroyed more coastal structures by water and waves than all the Florida coastal storms since 1975 combined. Nine years later, Hurricane Ivan pushed Pensacola’s water level to a record 9.54 feet, and in 2005 Hurricane Dennis came ashore on Santa Rosa Island itself. That history shows up in the claims.
Wind and surge in the same storm
On the island, the roof comes off and the surge comes through on the same night. The homeowners policy owes the wind damage and the flood policy owes the water. Photos of the water line and the roof, taken before cleanup starts, are what keep each side honest.
A Citizens policy with no flood policy behind it
If your home is insured by Citizens, Florida now requires you to carry flood insurance, phased in by the home's replacement cost. Without it, Citizens can refuse to cover the home, and surge damage has no policy to go to.
The permit nobody priced
Rebuilding a major structure or permanently repairing its foundation seaward of the state's Coastal Construction Control Line takes a state permit. Replacement windows and doors visible from the beach have to be tinted. Those are real costs, and an estimate that ignores them comes up short. Code-driven costs are generally covered only if you have law and ordinance coverage.
Condo unit or the whole building?
The association's master policy usually covers the structure and common areas. Your unit policy covers the inside and your belongings, depending on your condo documents. File each part with the policy that owes it.
How we handle your claim
On the island the steps are the same as anywhere else, with a few things we check first because of where the property is. Here’s what happens after you call.
Policy review
Before we come out, we read every policy on the property. On the island that is often more than one: a homeowners or Citizens policy for wind, a separate flood policy for surge, and for a condo, the association’s master policy alongside your unit policy. We read the endorsements and exclusions in each so we know which one covers which kind of damage.
Inspection
We inspect the property ourselves and photograph the roof, attic, interior and exterior. Where water came in, we photograph the water line as well, because it helps show what the wind did and what the surge did.
Our estimate
We write a line-item estimate of the full repair at current local prices. Costs that come from building rules, such as a state permit seaward of the Coastal Construction Control Line or tinted replacement windows and doors, are listed on their own lines so you can see them and check whether your policy has law and ordinance coverage.
Working with your insurer
We deal with your insurer on your behalf. If wind and surge both caused damage, we keep the two parts of the claim separate and send each to the policy that covers it. We answer the insurer’s requests and send the documentation behind your claim. Florida requires anyone inspecting for the insurer to give at least 48 hours’ notice before an on-site inspection (§626.854), so we can be at the property with you.
Appraisal, if it comes to that
When the only disagreement left is the amount of the loss, appraisal may be an option. Many policies let either side demand it: each side names an appraiser, the two appraisers choose an umpire, and an award signed by any two of the three sets the amount. Not every policy has an appraisal clause, so we check yours first.
Through the close of the claim
We keep up with the paperwork, any supplements and the deadlines until the claim is closed. Florida generally gives your insurer 60 days after it receives notice of a claim to pay or deny it, with limited exceptions (§627.70131).
What our clients say
Posted on Google
 Andrew Rodgers
Trustindex verifies that the original source of the review is Google.
Always helpful to our shared customers! Very knowledgeablePosted on Google jaroslav moravecI was very happy with the way David handled his business . They did what they said they would do. Great customer service . Communication was excellent . Would recommend to everyone.Posted on Google
 Chris AllenDavid is absolutely the best at what he does couldn't recommend him any more! This is someone I will contact every time I am in need of this service.Posted on Google
 BaileyWorking with David was a game changer. Having someone with so much knowledge in your corner is the only way to go about claims against insurance companies! A lot of work was needed to go up against my insurance company, and David and his team put it every ounce of effort needed to accomplish the goal!Posted on Google
 Wendy LockhartDavid and his team are fantastic. He was very professional and skilled at working with us and our insurance company to settle our claim. He was up front about the process and followed through on everything he informed us. He kept us up-to-date the entire time. I highly recommend.Posted on Google
 GT HodgesWe’re extremely grateful for the time, effort, and professionalism shown by David and Tamara in helping us with our home insurance claim. Their diligence, thoroughness, and clear communication made the entire process much smoother and less stressful. It’s rare to find someone who takes such care and pride in their work. We highly recommend their services to anyone.Posted on Google
 joan newmanDavid Otero was fist recommended to me by a friend who had been very satisfied with his services when she required an adjuster on a roof repair. He and his assistant, Tamara, responded immediately when I called him on the difficulty I was having after serious water damage in my home. David kept me fully informed on the repair request. In addition, he was able to secure funds for me that covered the necessary repairs for the damage my home incurred. I would recommend this team for any problems you may have in securing a just refund on damages to your property.Posted on Google
 David MMr. Otero got took care of me and my home with the insurance company told me no. Mr. Otero was aggressive, communicated and told me exactly what he would do and delivered. Thank youPosted on Google
 Anastasiia KoeppkeWorking with David was an outstanding experience from start to finish. He truly went above and beyond throughout the entire claim process. David took the time to explain every step clearly and made sure we fully understood our options. He was also personally involved in working with the umpire to ensure that all our expenses and damages were properly covered. His attention to detail and commitment to achieving the best possible outcome made a tremendous difference. What stood out most was how easy and professional David and his team were to work with. They were flexible and accommodating around our schedule, which was especially appreciated since we were also in the middle of home renovations. David’s responsiveness, patience, and genuine care for his clients turned what could have been a stressful situation into a smooth and successful process. We couldn’t have asked for better support. David is knowledgeable, trustworthy, and truly dedicated to his clients. We highly recommend him and his team to anyone in need of a public adjuster who will go the extra mile.
Areas we serve near Pensacola Beach
We handle claims on both barrier islands and across Escambia and Santa Rosa counties from our Pensacola office, and we come to every property for the inspection. See all service areas.
- Pensacola Beach
- Perdido Key
- Gulf Breeze
- Pensacola
- Navarre
Your rights in Florida
If Citizens insures your home, this one applies to you.
- Citizens requires flood insurance: Citizens has to require flood coverage on personal residential policies, phased in by the home’s replacement cost for policies effective on or after January 1, 2024 ($600,000 or more), January 1, 2025 ($500,000 or more), January 1, 2026 ($400,000 or more) and January 1, 2027 (all others). Homes in a FEMA special flood hazard area already need it. Policies that exclude wind and condominium unit-owner policies aren’t required to carry it (§627.351).
Your inspection and policy review on Pensacola Beach or Perdido Key are free.
Reporting deadlines (§627.70132). Report a new or reopened claim within 1 year of the date of loss. If you find more damage later on a claim you already filed, a supplemental claim has 18 months. For a hurricane, the date of loss is the landfall date.
This is general information, not legal advice. What applies to you depends on your policy and the facts of your claim.
Pensacola Beach Public Adjuster FAQs
My home is insured by Citizens. Do I have to carry flood insurance?
Very likely. Florida law requires flood coverage for Citizens personal residential policies, phased in by replacement cost, with every remaining home included for policies effective on or after January 1, 2027. Condo unit-owner policies and policies that exclude wind are the exceptions.
Wind and storm surge both damaged my house. How is it split?
Wind damage, and rain the wind drives inside, goes to your homeowners policy. Surge and rising water go to your flood policy. We document both separately so neither insurer can push its share onto the other.
Do I need a permit to rebuild on Pensacola Beach?
If the work is seaward of the Coastal Construction Control Line and involves rebuilding a major structure or permanently repairing its foundation, yes: a state emergency permit. Your contractor and local building officials can confirm what your project needs.
Who pays for the tinted glass the rules require?
Replacement windows and doors visible from the beach have to be tinted. If the requirement comes from code or permit rules, the extra cost is generally covered only under law and ordinance coverage, so check your policy for it.
I own a condo on the island. Which policy pays?
Usually both. The association’s master policy covers the building and common areas, and your unit policy covers the interior and your belongings, depending on your condo documents. We read both before anything is filed.
Do you cover Perdido Key?
Yes. Perdido Key is about 26 miles from our office, and we handle claims there and across the Pensacola area.
What does the free inspection include?
We come to the property, go through the damage and your policies with you, and tell you what we think the claim should cover. There’s no obligation to hire us.
How long do I have to file?
Report a new or reopened claim within 1 year of the date of loss, and a supplemental claim within 18 months. For a hurricane, the date of loss is the day it made landfall.
Storm or water damage on Pensacola Beach?
Get a free, no-obligation damage inspection and policy evaluation. Call (850) 285-0405.