Navarre Public Adjuster
Navarre has taken more than one direct hit from a hurricane. We work for you, not your insurance company. Free, no-obligation damage inspection and policy evaluation.
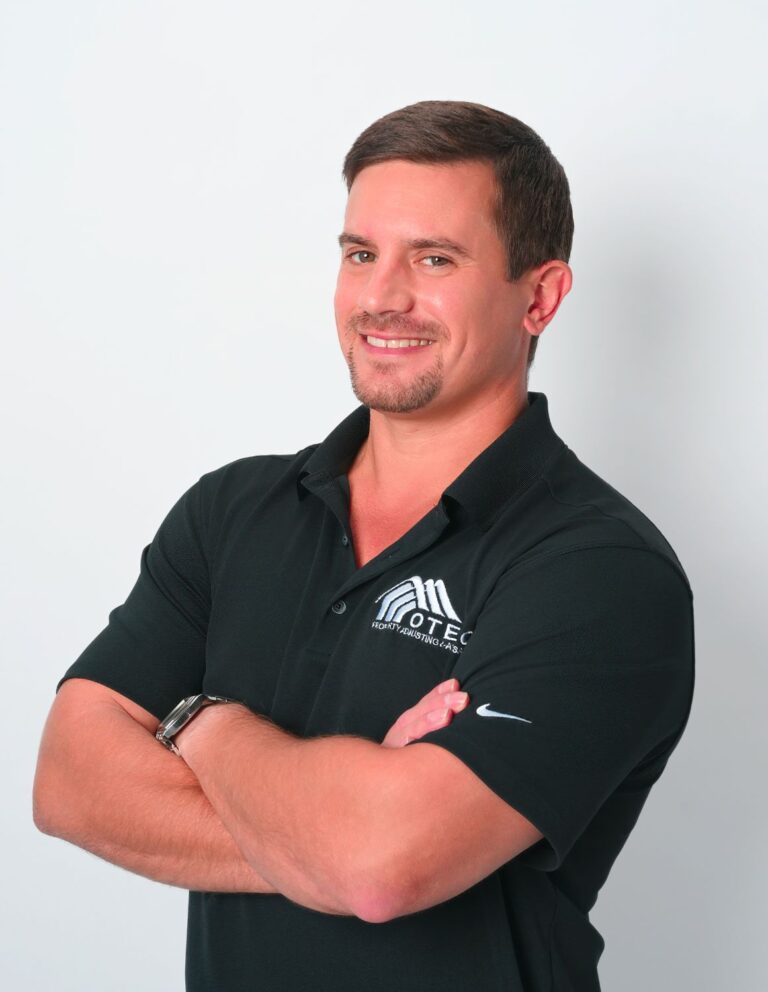
David Otero, President
Licensed Florida public insurance adjuster
7+ years of claims experience
- License W605057
- FAPIA member
- Windstorm Insurance Network member
- Rated 5.0 on Google
- Free inspection
A Navarre Public Adjuster who knows its storm history
Otero Property Adjusting & Appraisals Inc represents homeowners, condo owners, landlords and business owners in Navarre and on Navarre Beach. We work only for policyholders.
Our office on West Michigan Ave in Pensacola is about 33 miles away along US 98. We inspect every property in person. When you call, you talk to our Pensacola team, and David Otero oversees your claim.
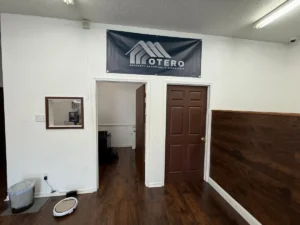
- 3105 West Michigan Ave, Pensacola, FL 32526
- (850) 285-0405
Tell us about the damage. We will follow up to schedule your free, no-obligation inspection.
Claims we handle in Navarre
Hurricane Dennis came ashore on Santa Rosa Island near Navarre in 2005. In 2020, Hurricane Sally dropped 19.95 inches of rain here, the most in Santa Rosa County. Storms cause a lot of the claims here, but not all of them.
Hurricane damage
Dennis made landfall as a Category 3 storm with 120 mph winds. Storms like that damage roofs, siding, windows and everything inside, so we document the whole loss before repairs start.
Water damage
Sally was a rain storm. Water forced through roofs, windows and walls by wind is usually covered, even when an insurer calls it seepage.
Roof leaks
After several storms, insurers like to blame a leak on old damage or past repairs. We separate the new damage from the old.
Flood damage
Surge on Navarre Beach and rising water along Santa Rosa Sound count as flood damage, which needs a separate flood policy.
Mold damage
In this climate, mold can follow a leak quickly. Many policies cap it, so it has to be tied to a covered cause and reported promptly.
Commercial property claims
Beach rentals, restaurants and shops along Navarre Parkway can claim building damage and, with the right coverage, lost income.
Wind damage
Gusts pull off shingles and soffits and push rain through the gaps. That damage belongs on the wind claim.
Fire and smoke damage
Lightning strikes and electrical or kitchen fires can spread smoke and soot through a whole house or condo building.
Where Navarre claims come up short
When the same area gets hit again and again, the disputes are about history and timing.
Old damage vs. new damage
After repeat storms, insurers blame "prior damage" or earlier repairs. Keep records of past claims and repairs. We use them to show what this storm did.
Rain called something else
Wind-driven rain is usually covered, but insurers may label it flood, seepage or poor maintenance. How the entry points are documented decides the outcome.
Beach condos and rentals
On Navarre Beach, damage splits between the association's master policy and your unit policy, and rental income is a separate coverage. Owners who live elsewhere need someone to inspect for them.
Missed deadlines
People wait to see what the insurer pays. Florida requires new or reopened claims within 1 year of the date of loss, and supplemental claims within 18 months. Waiting too long can cost you the claim.
How we handle your claim
Your insurer’s adjuster works for the insurer. We work for you, and we start by looking at what earlier storms and repairs left behind.
Policy review
We read the whole policy, including endorsements and exclusions, before the inspection, so we know what it says about the type of damage you have.
Inspection
We inspect the property ourselves and photograph the roof, attic, interior and exterior, so every area of damage is documented.
Our estimate
We write a line-item estimate for the full repair at current local prices.
Working with your insurer
We communicate with your insurer on your behalf, answer its requests and present the documentation that supports your claim. Anyone inspecting for the insurer must give at least 48 hours’ notice before an on-site inspection (§626.854), so we can be there with you.
Appraisal, if it comes to that
If you and the insurer still disagree on the amount, many policies let either side demand appraisal. Each side picks an appraiser, and those two choose an umpire. An award signed by any two of them sets the amount of the loss. Check your policy first, because not every policy has this clause.
Through the close of the claim
We handle the paperwork, supplements and deadlines through the end of the claim. Florida generally gives your insurer 60 days after it receives notice of a claim to pay or deny it, with limited exceptions (§627.70131).
What our clients say
Posted on GoogleTrustindex verifies that the original source of the review is Google. I was very happy with the way David handled his business . They did what they said they would do. Great customer service . Communication was excellent . Would recommend to everyone.Posted on GoogleTrustindex verifies that the original source of the review is Google. David is absolutely the best at what he does couldn't recommend him any more! This is someone I will contact every time I am in need of this service.Posted on GoogleTrustindex verifies that the original source of the review is Google. Working with David was a game changer. Having someone with so much knowledge in your corner is the only way to go about claims against insurance companies! A lot of work was needed to go up against my insurance company, and David and his team put it every ounce of effort needed to accomplish the goal!Posted on GoogleTrustindex verifies that the original source of the review is Google. David and his team are fantastic. He was very professional and skilled at working with us and our insurance company to settle our claim. He was up front about the process and followed through on everything he informed us. He kept us up-to-date the entire time. I highly recommend.Posted on GoogleTrustindex verifies that the original source of the review is Google. We’re extremely grateful for the time, effort, and professionalism shown by David and Tamara in helping us with our home insurance claim. Their diligence, thoroughness, and clear communication made the entire process much smoother and less stressful. It’s rare to find someone who takes such care and pride in their work. We highly recommend their services to anyone.Posted on GoogleTrustindex verifies that the original source of the review is Google. David Otero was fist recommended to me by a friend who had been very satisfied with his services when she required an adjuster on a roof repair. He and his assistant, Tamara, responded immediately when I called him on the difficulty I was having after serious water damage in my home. David kept me fully informed on the repair request. In addition, he was able to secure funds for me that covered the necessary repairs for the damage my home incurred. I would recommend this team for any problems you may have in securing a just refund on damages to your property.Posted on GoogleTrustindex verifies that the original source of the review is Google. Mr. Otero got took care of me and my home with the insurance company told me no. Mr. Otero was aggressive, communicated and told me exactly what he would do and delivered. Thank youPosted on GoogleTrustindex verifies that the original source of the review is Google. Working with David was an outstanding experience from start to finish. He truly went above and beyond throughout the entire claim process. David took the time to explain every step clearly and made sure we fully understood our options. He was also personally involved in working with the umpire to ensure that all our expenses and damages were properly covered. His attention to detail and commitment to achieving the best possible outcome made a tremendous difference. What stood out most was how easy and professional David and his team were to work with. They were flexible and accommodating around our schedule, which was especially appreciated since we were also in the middle of home renovations. David’s responsiveness, patience, and genuine care for his clients turned what could have been a stressful situation into a smooth and successful process. We couldn’t have asked for better support. David is knowledgeable, trustworthy, and truly dedicated to his clients. We highly recommend him and his team to anyone in need of a public adjuster who will go the extra mile.Posted on GoogleTrustindex verifies that the original source of the review is Google. I would give 10 stars if I could. David Otero has been awesome. Prior to David, I was working with another PA that did a really bad job. I was referred to David by a friend, and he turned my situation around. I live in St Petersburg, and got rocked by the floods from the hurricanes last year. He went to town on the insurance company, and got me a lot more than their insurance original offer. Great communication, and will make sure to clearly lay out your options throughout the process. David will go as far as you like him to with the insurance company. I will definitely be working with David going forward as my PA, and would recommend to anyone needing a PA.Posted on GoogleTrustindex verifies that the original source of the review is Google. Otero Property Adjusting & Appraisals Inc. has helped several of our residential clients. The homeowners are very pleased with their services. We recommend using Otero Property Adjusting & Appraisals Inc.
Areas we serve near Navarre
From our Pensacola office we serve Navarre, Santa Rosa County and the Panhandle, and we handle claims throughout Florida. See all service areas.
Your rights in Florida
In a repeat-storm area, deadlines matter as much as damage.
The inspection and policy review are free.
Deadlines to know (§627.70132). A new or reopened claim has to be reported within 1 year of the date of loss. A supplemental claim, for more damage found later on a claim you already filed, has 18 months.
This is general information, not legal advice. Your policy and the facts of your claim decide what applies to you.
Navarre Public Adjuster FAQs
My house was damaged in an earlier storm too. Will the insurer blame the old damage?
It may try. Photos, invoices and past claim records help show what was repaired and what’s new. We inspect for fresh damage and document the difference.
Water came in during heavy rain, but the house didn't flood. Is that covered?
Often, yes. Rain driven in by wind through a damaged roof, window or wall is usually treated as wind damage, not flood. Policy wording varies, so we review yours with you.
Do you handle Navarre Beach condos and rentals?
Yes. We work through both the master policy and your unit policy, and we check whether you have loss-of-rent coverage.
How long do I have to file after a hurricane in Florida?
Within 1 year of the date of loss for a new or reopened claim, and 18 months for a supplemental claim.
Can I hire a public adjuster after the insurance company already paid me?
Yes. If the payment is short or more damage appears, a supplemental claim can be filed within 18 months of the date of loss.
Do you travel to Navarre for inspections?
Yes. We’re about 33 miles away in Pensacola, and every inspection happens at your property.
I'm stationed at Hurlburt Field and could get new orders. Can you keep my claim going?
Yes. A public adjuster can handle inspections, paperwork and meetings with the insurer while you’re away.
Storm or water damage in Navarre?
Get a free, no-obligation damage inspection and policy evaluation. We work for you, not your insurance company.