Panama City Public Adjuster
Years after Hurricane Michael, plenty of Bay County owners still don’t know why their check came in lower than the insurer’s own estimate. We work for you, not your insurance company. Free, no-obligation damage inspection and policy evaluation.
David Otero, President
Licensed Florida public insurance adjuster
7+ years of claims experience
- License W605057
- FAPIA member
- Windstorm Insurance Network member
- Rated 5.0 on Google
- Free inspection
A Panama City Public Adjuster, 140 miles from our office
Otero Property Adjusting & Appraisals Inc represents homeowners, landlords, condo owners and business owners in Panama City and across Bay County. We work only for policyholders, never for insurance companies.
Our office is on West Michigan Ave in Pensacola, about 140 miles west of Panama City. We don’t have a Bay County office, so we schedule your inspection and drive over for it. When you call, you talk to our Pensacola team, and David Otero oversees your claim.
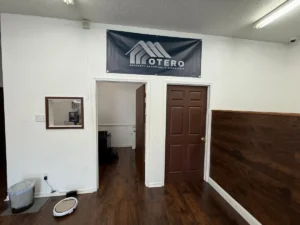
- 3105 West Michigan Ave, Pensacola, FL 32526
- (850) 285-0405
Tell us what happened, and if you already have an estimate or a payment letter from your insurer, mention it. Those two pages tell us a lot.
Claims we handle in Panama City
Most Panama City claims come down to wind, water or a payment that doesn’t add up. Find yours below.
Hurricane damage
Hurricane claims carry their own deductible and their own fights over wind versus water. Both sides of the loss need to be documented separately.
Roof and wind damage
Storms off St. Andrew Bay peel shingles and crack tile, and the rain finds the gap. Water that wind lets into the house belongs on the wind claim.
Commercial property claims
Offices, shops, restaurants and rental buildings carry commercial policies with their own limits and conditions, including coinsurance.
Income loss claims
When a business has to close for repairs, the lost income can be part of the claim. It has to be shown with records, not estimated.
Water damage
Burst pipes, failed water heaters and AC overflows soak floors and walls from the inside. Where the water started decides what's covered.
Flood damage
Rising water from the bay or a storm surge is a flood claim under a flood policy. Keeping it apart protects the wind side of your claim.
Mold damage
Bay County humidity turns a hidden leak into mold quickly. Many policies cap mold coverage, so the date the water started matters.
Fire and smoke damage
Smoke and soot spread well past the room that burned. Cleaning, contents and the rebuild all belong in the claim.
Where Panama City claims come up short
Hurricane Michael came ashore near Mexico Beach on October 10, 2018. The National Weather Service recorded a 139 mph gust at Tyndall Air Force Base, just east of the city, before the instruments stopped reporting, and catastrophic wind damage reached well inland. Then in January 2024, an EF3 tornado tore through western Panama City. Owners here have been through more claims than most, and the same few problems keep coming back.
The check doesn't match the estimate
The insurer writes a detailed estimate, then pays less, and the letter doesn't say why. Under Florida law, when an insurer pays less than its own detailed estimate, it has to explain the difference in writing. Ask for that explanation before you accept the number.
Old claim money used against a new claim
If a past claim was paid and the money wasn't spent on repairs, the insurer may argue the new damage was already paid for. Receipts, permits and photos of the finished work are what answer that.
A commercial limit that never caught up
Rebuilding costs climbed after Michael. If a building's insured value didn't keep up, a coinsurance clause can reduce every payment on the claim, not only the big ones. Check your limit against today's cost to rebuild.
The tree is two different claims
A pine through the roof means repairs to the house, and separately, getting the tree off it. Many policies limit what they'll pay to remove trees, so each part has to be claimed on its own.
How we handle your claim
You’ll get the same six steps whether you’re 10 miles from our office or 140. Here’s how a Panama City claim moves.
Policy review
We read the whole policy, including endorsements and exclusions, before the inspection, so we know what it says about the type of damage you have.
Inspection
We inspect the property ourselves and photograph the roof, attic, interior and exterior, so every area of damage is documented.
Our estimate
We write a line-item estimate for the full repair at current local prices.
Working with your insurer
We communicate with your insurer on your behalf, answer its requests and present the documentation that supports your claim. Anyone inspecting for the insurer must give at least 48 hours’ notice before an on-site inspection (§626.854), so we can be there with you.
Appraisal, if it comes to that
If you and the insurer still disagree on the amount, many policies let either side demand appraisal. Each side picks an appraiser, and those two choose an umpire. An award signed by any two of them sets the amount of the loss. Check your policy first, because not every policy has this clause.
Through the close of the claim
We handle the paperwork, supplements and deadlines through the end of the claim. Florida generally gives your insurer 60 days after it receives notice of a claim to pay or deny it, with limited exceptions (§627.70131).
What our clients say
Posted on GoogleTrustindex verifies that the original source of the review is Google. I was very happy with the way David handled his business . They did what they said they would do. Great customer service . Communication was excellent . Would recommend to everyone.Posted on GoogleTrustindex verifies that the original source of the review is Google. David is absolutely the best at what he does couldn't recommend him any more! This is someone I will contact every time I am in need of this service.Posted on GoogleTrustindex verifies that the original source of the review is Google. Working with David was a game changer. Having someone with so much knowledge in your corner is the only way to go about claims against insurance companies! A lot of work was needed to go up against my insurance company, and David and his team put it every ounce of effort needed to accomplish the goal!Posted on GoogleTrustindex verifies that the original source of the review is Google. David and his team are fantastic. He was very professional and skilled at working with us and our insurance company to settle our claim. He was up front about the process and followed through on everything he informed us. He kept us up-to-date the entire time. I highly recommend.Posted on GoogleTrustindex verifies that the original source of the review is Google. We’re extremely grateful for the time, effort, and professionalism shown by David and Tamara in helping us with our home insurance claim. Their diligence, thoroughness, and clear communication made the entire process much smoother and less stressful. It’s rare to find someone who takes such care and pride in their work. We highly recommend their services to anyone.Posted on GoogleTrustindex verifies that the original source of the review is Google. David Otero was fist recommended to me by a friend who had been very satisfied with his services when she required an adjuster on a roof repair. He and his assistant, Tamara, responded immediately when I called him on the difficulty I was having after serious water damage in my home. David kept me fully informed on the repair request. In addition, he was able to secure funds for me that covered the necessary repairs for the damage my home incurred. I would recommend this team for any problems you may have in securing a just refund on damages to your property.Posted on GoogleTrustindex verifies that the original source of the review is Google. Mr. Otero got took care of me and my home with the insurance company told me no. Mr. Otero was aggressive, communicated and told me exactly what he would do and delivered. Thank youPosted on GoogleTrustindex verifies that the original source of the review is Google. Working with David was an outstanding experience from start to finish. He truly went above and beyond throughout the entire claim process. David took the time to explain every step clearly and made sure we fully understood our options. He was also personally involved in working with the umpire to ensure that all our expenses and damages were properly covered. His attention to detail and commitment to achieving the best possible outcome made a tremendous difference. What stood out most was how easy and professional David and his team were to work with. They were flexible and accommodating around our schedule, which was especially appreciated since we were also in the middle of home renovations. David’s responsiveness, patience, and genuine care for his clients turned what could have been a stressful situation into a smooth and successful process. We couldn’t have asked for better support. David is knowledgeable, trustworthy, and truly dedicated to his clients. We highly recommend him and his team to anyone in need of a public adjuster who will go the extra mile.Posted on GoogleTrustindex verifies that the original source of the review is Google. I would give 10 stars if I could. David Otero has been awesome. Prior to David, I was working with another PA that did a really bad job. I was referred to David by a friend, and he turned my situation around. I live in St Petersburg, and got rocked by the floods from the hurricanes last year. He went to town on the insurance company, and got me a lot more than their insurance original offer. Great communication, and will make sure to clearly lay out your options throughout the process. David will go as far as you like him to with the insurance company. I will definitely be working with David going forward as my PA, and would recommend to anyone needing a PA.Posted on GoogleTrustindex verifies that the original source of the review is Google. Otero Property Adjusting & Appraisals Inc. has helped several of our residential clients. The homeowners are very pleased with their services. We recommend using Otero Property Adjusting & Appraisals Inc.
Areas we serve near Panama City
We handle claims across Bay County and the rest of the Panhandle from our Pensacola office, and every inspection happens at the property. See all service areas.
- Panama City
- Panama City Beach
- Destin
- Niceville
- Fort Walton Beach
Your rights in Florida
If your payment came in under the insurer’s estimate, this is the rule to know.
- Pay or deny within 60 days, and explain it in writing: after receiving notice of an initial, reopened or supplemental claim, the insurer has 60 days to pay or deny it, or part of it, unless the delay is caused by factors beyond its control. It has to give you a reasonable written explanation of the decision, and if it pays less than its own detailed estimate, it has to explain the difference in writing (§627.70131).
The inspection and policy review are free.
Deadlines to know (§627.70132). A new or reopened claim has to be reported within 1 year of the date of loss. A supplemental claim, for more damage found later on a claim you already filed, has 18 months.
This is general information, not legal advice. Your policy and the facts of your claim decide what applies to you.
Panama City Public Adjuster FAQs
My payment is less than the insurer's estimate. Do they have to explain it?
Yes. If your insurer pays less than its own detailed estimate of the loss, Florida law requires a reasonable written explanation of the difference. If you didn’t get one, ask for it in writing.
My Michael claim was paid years ago. Can the insurer use that against a new claim?
It can try, especially if the earlier payment wasn’t used for repairs. Showing the work was finished, with receipts, permits and photos, separates the old loss from the new one.
A tree fell on my house. What does insurance cover?
Usually the damage the tree caused to the house is covered under the dwelling part of your policy. Removing the tree is often treated separately and may have its own limit. Check both before you hire a crew.
My building's insurance limit hasn't changed since the rebuild. Is that a problem?
It can be. If a commercial policy has a coinsurance clause and the limit is too low for today’s rebuilding cost, payments on a claim can be reduced. Review the limit with your agent before a loss, not after.
How long does my insurer have to pay or deny my claim?
Sixty days after it receives notice of your claim, unless factors beyond its control cause the delay. The decision has to come with a reasonable written explanation.
You're based in Pensacola. Do you come to Panama City?
Yes. Our office is about 140 miles away, and we schedule the inspection at your property.
What does the free inspection include?
We look at the damage with you, review your policy, and tell you where we think the claim stands. There’s no obligation to hire us afterward.
Do you cover Panama City Beach and the rest of Bay County?
Yes. We handle claims in Panama City Beach and across Bay County, and anywhere else in Florida.
Storm or water damage in Panama City?
Get a free, no-obligation damage inspection and policy evaluation. Call (850) 285-0405.