Panama City Beach Public Adjuster
After Hurricane Michael and the January 2024 tornado, plenty of Bay County claims hinge on one question: which deductible applies? We work for you, not your insurance company. Free, no-obligation damage inspection and policy evaluation.
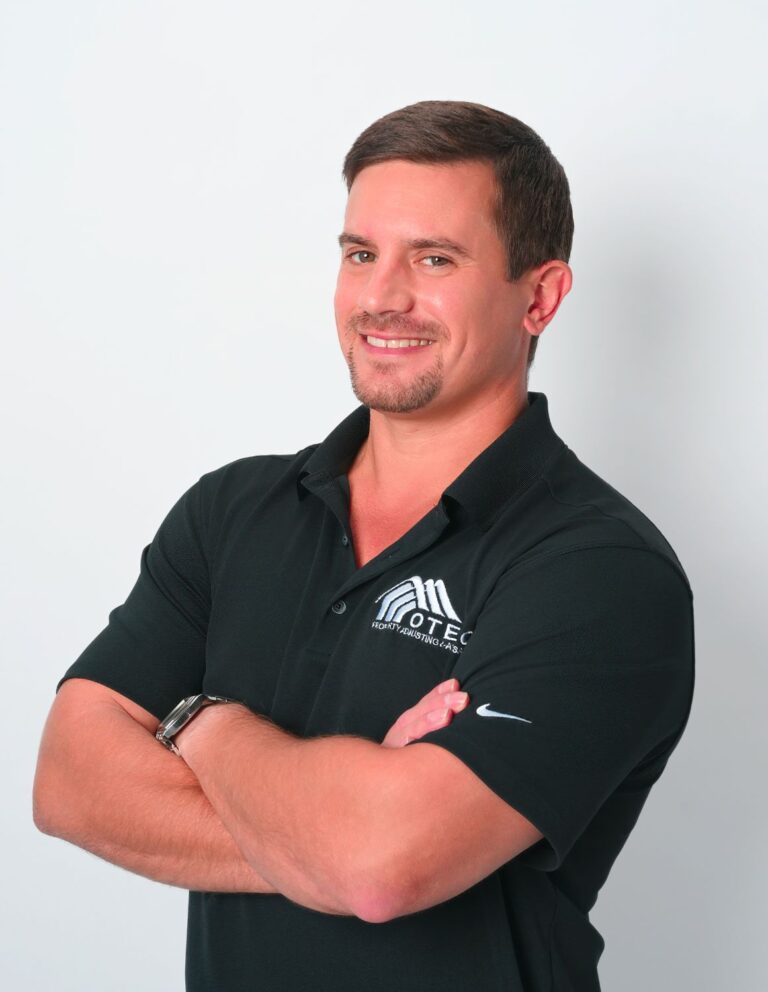
David Otero, President
Licensed Florida public insurance adjuster
7+ years of claims experience
- License W605057
- FAPIA member
- Windstorm Insurance Network member
- Rated 5.0 on Google
- Free inspection
A Panama City Beach Public Adjuster who comes to you
Otero Property Adjusting & Appraisals Inc represents homeowners, condo owners, rental owners and business owners in Panama City Beach and across Bay County. We work only for policyholders, never for insurance companies.
Our office is on West Michigan Ave in Pensacola, about 130 miles west, so we’re not around the corner. We schedule in-person inspections in Panama City Beach and come to your property. When you call, you talk to our Pensacola team, and David Otero oversees your claim.
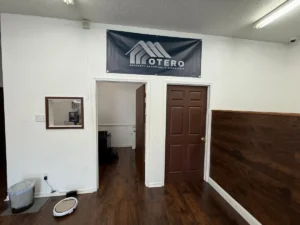
- 3105 West Michigan Ave, Pensacola, FL 32526
- (850) 285-0405
Tell us what happened, when it happened, and whether it was a hurricane or a tornado if you know. We’ll set up your free inspection.
Claims we handle in Panama City Beach
Wind is the common thread in Bay County claims, whether it came from a hurricane or a tornado. Find your type of damage below.
Tornado damage
A tornado can wreck one street and skip the next. The claim has to show the path it took and what it did to your house.
Hurricane damage
Hurricane claims bring their own deductible, often a percentage of your dwelling coverage, and it isn't always applied correctly.
Commercial property claims
Rental condos, hotels and shops lose income while they're closed for repairs. The income side belongs in the claim with the building.
Roof leaks
Salt air and years of storms wear a roof down, and insurers like to blame age. New storm damage has to be shown apart from old wear.
Water damage
Burst pipes and AC leaks in one unit can spread to the units below, and each unit's share depends on where the water started.
Flood damage
Surge and rising water go to a flood policy, not your homeowners policy. We keep them separate so wind damage isn't written off as flood.
Mold damage
Beach humidity can turn a hidden leak into mold within days. Many policies cap mold coverage, so the cause needs to be on record early.
Fire and smoke damage
In a condo tower, smoke travels through halls and shared ducts. We claim the cleaning and contents in every unit it touched.
Where Panama City Beach claims come up short
Bay County has been hit by two very different wind events in six years. Hurricane Michael came ashore near Mexico Beach on October 10, 2018, as a Category 5 with 160 mph winds, the strongest landfall on record in the Florida Panhandle. Then on January 9, 2024, an EF3 tornado with peak winds near 140 mph tore a 5.22-mile path through Lower Grand Lagoon, next to Panama City Beach, and western Panama City. It destroyed a beachfront home, ripped roofs and walls off homes and condos, and caused more than $15 million in damage. It was Bay County’s first EF3 since the 1970s.
Those two storms shape the claim problems below.
The wrong deductible
Before writing a homeowners policy, Florida insurers have to offer hurricane deductibles of $500 or 2%, 5% or 10% of the dwelling coverage. On a $400,000 home, a 2% deductible is $8,000 before the insurer pays anything. It's only supposed to apply to hurricane wind losses inside a set window. A January tornado falls outside it and should use your regular deductible. If your insurer applied the hurricane deductible to a winter tornado claim, that's worth a second look.
Tornado damage that doesn't look like the rest of the street
Tornado damage is narrow and violent. The house next door can look fine while yours lost a wall. Insurers sometimes push back on damage that doesn't match the neighborhood, so the documentation has to show the path and how the wind hit your house.
Beach condos and rentals
A condo building has a master policy for the structure and your unit policy for the inside, depending on the association's documents. If the unit is a rental, lost bookings may be covered too, but only if your policy includes it and you can show the income. Owners who live out of town often never see the damage in person.
Old Michael repairs blamed for new damage
Many homes here were rebuilt after Michael. When new damage shows up, insurers may say it's left over from 2018 or from a repair that wasn't done right. Repair invoices, permits and photos from after the rebuild are what answer that.
How we handle your claim
The insurer’s adjuster works for the insurance company. We work only for you. Here’s what happens after you call, step by step.
Policy review
We read the whole policy, including endorsements and exclusions, before the inspection, so we know what it says about the type of damage you have.
Inspection
We inspect the property ourselves and photograph the roof, attic, interior and exterior, so every area of damage is documented.
Our estimate
We write a line-item estimate for the full repair at current local prices.
Working with your insurer
We communicate with your insurer on your behalf, answer its requests and present the documentation that supports your claim. Anyone inspecting for the insurer must give at least 48 hours’ notice before an on-site inspection (§626.854), so we can be there with you.
Appraisal, if it comes to that
If you and the insurer still disagree on the amount, many policies let either side demand appraisal. Each side picks an appraiser, and those two choose an umpire. An award signed by any two of them sets the amount of the loss. Check your policy first, because not every policy has this clause.
Through the close of the claim
We handle the paperwork, supplements and deadlines through the end of the claim. Florida generally gives your insurer 60 days after it receives notice of a claim to pay or deny it, with limited exceptions (§627.70131).
What our clients say
Posted on Google
 Andrew Rodgers
Trustindex verifies that the original source of the review is Google.
Always helpful to our shared customers! Very knowledgeablePosted on Google jaroslav moravecI was very happy with the way David handled his business . They did what they said they would do. Great customer service . Communication was excellent . Would recommend to everyone.Posted on Google
 Chris AllenDavid is absolutely the best at what he does couldn't recommend him any more! This is someone I will contact every time I am in need of this service.Posted on Google
 BaileyWorking with David was a game changer. Having someone with so much knowledge in your corner is the only way to go about claims against insurance companies! A lot of work was needed to go up against my insurance company, and David and his team put it every ounce of effort needed to accomplish the goal!Posted on Google
 Wendy LockhartDavid and his team are fantastic. He was very professional and skilled at working with us and our insurance company to settle our claim. He was up front about the process and followed through on everything he informed us. He kept us up-to-date the entire time. I highly recommend.Posted on Google
 GT HodgesWe’re extremely grateful for the time, effort, and professionalism shown by David and Tamara in helping us with our home insurance claim. Their diligence, thoroughness, and clear communication made the entire process much smoother and less stressful. It’s rare to find someone who takes such care and pride in their work. We highly recommend their services to anyone.Posted on Google
 joan newmanDavid Otero was fist recommended to me by a friend who had been very satisfied with his services when she required an adjuster on a roof repair. He and his assistant, Tamara, responded immediately when I called him on the difficulty I was having after serious water damage in my home. David kept me fully informed on the repair request. In addition, he was able to secure funds for me that covered the necessary repairs for the damage my home incurred. I would recommend this team for any problems you may have in securing a just refund on damages to your property.Posted on Google
 David MMr. Otero got took care of me and my home with the insurance company told me no. Mr. Otero was aggressive, communicated and told me exactly what he would do and delivered. Thank youPosted on Google
 Anastasiia KoeppkeWorking with David was an outstanding experience from start to finish. He truly went above and beyond throughout the entire claim process. David took the time to explain every step clearly and made sure we fully understood our options. He was also personally involved in working with the umpire to ensure that all our expenses and damages were properly covered. His attention to detail and commitment to achieving the best possible outcome made a tremendous difference. What stood out most was how easy and professional David and his team were to work with. They were flexible and accommodating around our schedule, which was especially appreciated since we were also in the middle of home renovations. David’s responsiveness, patience, and genuine care for his clients turned what could have been a stressful situation into a smooth and successful process. We couldn’t have asked for better support. David is knowledgeable, trustworthy, and truly dedicated to his clients. We highly recommend him and his team to anyone in need of a public adjuster who will go the extra mile.
Areas we serve near Panama City Beach
We handle claims across Bay County, along the Emerald Coast and throughout Florida from our Pensacola office, and the inspection always takes place at your property. See all service areas.
- Panama City Beach
- Panama City
- Destin
- Niceville
- Fort Walton Beach
Your rights in Florida
If a tornado or a winter storm damaged your property, start with the deductible rule below.
- Hurricane deductible window: a hurricane deductible applies to windstorm losses during a hurricane, from the time the National Hurricane Center issues a hurricane warning for any part of Florida until 72 hours after the last hurricane watch or warning for Florida ends. Wind damage outside that window, like the January 2024 tornado, generally falls under your regular deductible (§627.4025).
The inspection and policy review are free.
Deadlines to know (§627.70132). A new or reopened claim has to be reported within 1 year of the date of loss. A supplemental claim, for more damage found later on a claim you already filed, has 18 months.
This is general information, not legal advice. Your policy and the facts of your claim decide what applies to you.
Panama City Beach Public Adjuster FAQs
A tornado damaged my home. Does my hurricane deductible apply?
Only if the tornado hit during a hurricane, inside the window that starts with a hurricane warning for any part of Florida and ends 72 hours after the last watch or warning. A tornado outside that window, like the one in January 2024, generally uses your regular deductible.
How do I know which deductible my insurer used?
Look at your claim payment letter or the estimate summary. It should list the deductible taken off. Compare that amount to the deductibles on your declarations page. If the hurricane deductible was used on a tornado claim, we can review it with you.
My condo is a vacation rental. What can I claim?
The damage inside your unit and your belongings, under your unit policy. Lost rental income too, if your policy includes loss of rents and you can show the bookings you lost. The building itself is usually on the association’s master policy.
My home was repaired after Michael. Will the insurer blame the old damage?
It might try. Keep your repair invoices, permits and post-repair photos, because they show the work was done and done right. New damage on top of a finished repair is a new loss.
You're based in Pensacola. Do you come to Panama City Beach?
Yes. Our office is about 130 miles away, and we schedule in-person inspections at your property.
What does the free inspection include?
An in-person look at the damage, a review of your policy, and a straight answer on what we think your claim is missing. There’s no obligation after that.
My claim was denied or underpaid. Can you help?
In many cases. A denial letter or a low payment can still be challenged. We go back through the property, find what the insurer’s estimate left out, and pursue it as a reopened or supplemental claim while Florida’s deadlines allow. When the fight is only about the dollar amount, appraisal can settle it.
Is it too late to file for older storm damage?
It depends on the date of loss. Florida allows 1 year from that date to report a new or reopened claim and 18 months for a supplemental one, and a hurricane’s date of loss is the day it made landfall. Michael’s windows have closed, but damage from a more recent storm may still be in time.
Storm or water damage in Panama City Beach?
Get a free, no-obligation damage inspection and policy evaluation. Call (850) 285-0405.